A no-cost Medicare consultation gives you an opportunity to compare coverage choices without paying a separate consultation fee. A Medicare insurance agent can review your doctors, prescriptions, preferred pharmacies, budget, current coverage, and healthcare priorities before discussing available options. The goal should be to understand how plans differ—not simply choose the plan with the lowest premium or the longest list of extra benefits.
At iWill Advisors, we offer no-cost consultations for Medicare beneficiaries and families who want help understanding their coverage choices. As a Medicare Insurance Agency in South Florida, we compare options from multiple insurers represented by our agency and help clients look beyond plan names and advertisements to the details that affect how coverage may actually work.
That review is particularly important because Medicare decisions can involve more than monthly premiums. Doctor networks, prescription formularies, pharmacies, deductibles, copayments, prior authorization rules, travel needs, and enrollment rights may all affect whether an option is practical for a particular person.
What Does a No-Cost Medicare Consultation Mean?
A no-cost consultation means you are not charged a separate fee by our agency for sitting down with us to review Medicare insurance options.
That does not mean insurance agents necessarily work without compensation. For Medicare Advantage and Part D plans, insurance companies may compensate agents or brokers when an eligible beneficiary enrolls in a plan they represent. Medicare regulates agent and broker compensation and marketing practices.
This distinction is important because consumers should understand who they are speaking with.
An insurance agency can help compare products from the insurers it represents. That is different from a government counseling service, which provides free and unbiased Medicare counseling and is not connected to an insurance company or health plan.
Both can be useful resources, but they serve somewhat different roles.
What Should a Medicare Consultation Review?
A useful consultation should start with your actual healthcare needs rather than a list of plan benefits.
Important information to review includes:
- Your current Medicare coverage
- Primary-care doctors
- Specialists
- Hospitals or healthcare systems you prefer
- Prescription medications, including names and dosages
- Preferred pharmacies
- Expected healthcare use
- Monthly premium preferences
- Copayments, coinsurance, deductibles, and maximum out-of-pocket exposure
- Travel or seasonal-residence needs
- Other insurance or assistance, such as employer coverage, Medicaid, or Extra Help
The purpose is not to predict every healthcare need you may have in the future. It is to compare available coverage using the information that is known today.
Why Are Your Doctors Important When Comparing Medicare Plans?
Provider access can be one of the biggest practical differences between Original Medicare and Medicare Advantage.
With Original Medicare, beneficiaries generally can use doctors and hospitals throughout the United States that participate in Medicare. Medicare Advantage plans may use provider networks and service areas, and non-emergency care outside the network may not be covered or may cost more depending on the plan.
For someone who regularly sees a primary-care physician, cardiologist, oncologist, orthopedic specialist, or another provider, checking participation can be more important than focusing on an additional benefit the person may rarely use.
During a consultation, bring the names of the doctors and specialists you want to continue seeing.
Provider directories can change, so participation should also be reconfirmed with the plan and, when appropriate, the provider before enrollment.
Why Should Prescriptions Be Reviewed Individually?
Medicare drug plans and Medicare Advantage plans with prescription coverage use formularies, which are lists of covered drugs.
Two plans may both cover prescription drugs while treating the same medication differently.
Differences may involve:
- Whether a medication appears on the formulary
- The formulary tier
- Copayment or coinsurance
- Prior authorization
- Step therapy
- Quantity limits
- Preferred pharmacy arrangements
That is why simply asking whether a plan “includes drug coverage” is not enough.
Bring an up-to-date medication list to a consultation, including the exact drug names, dosages, frequency, and preferred pharmacy. Medicare’s own Plan Compare tool similarly uses prescription and pharmacy information to provide more useful cost estimates.
What Medicare Coverage Options Can Be Compared?
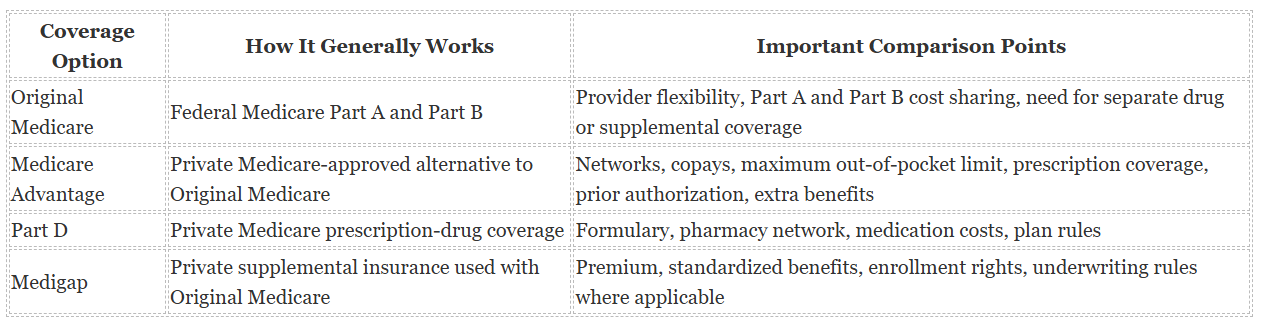
A person generally does not combine Medigap with Medicare Advantage. Medigap is designed to help with certain out-of-pocket costs associated with Original Medicare.
Our Medicare solutions consultations can help explain these distinctions before you compare specific insurance products.
Why Isn’t the Lowest Premium Automatically the Best Choice?
A low monthly premium can be attractive, but premium is only one part of healthcare spending.
Depending on the coverage, beneficiaries may also need to consider:
- Medical deductibles
- Specialist copayments
- Hospital cost sharing
- Prescription costs
- Out-of-network costs
- Maximum annual out-of-pocket limits for Medicare Advantage
- Separate premiums for supplemental or drug coverage
A plan with a lower premium may fit one person’s needs very well while another person may prefer more predictable cost sharing or broader provider flexibility.
A Medicare Insurance Advisor should explain these tradeoffs rather than treating premium alone as the deciding factor.
When Can You Enroll in or Change Medicare Coverage?
Different Medicare enrollment periods serve different purposes.
Initial Enrollment Period
For most people first becoming eligible at age 65, the Medicare Initial Enrollment Period lasts seven months: the three months before the month you turn 65, the month you turn 65, and the three months afterward.
Rules can differ if you delay Part B because you have qualifying employer coverage or become Medicare-eligible for another reason.
Medicare Open Enrollment
Medicare Open Enrollment occurs every year from October 15 through December 7.
During this period, eligible beneficiaries can make changes such as switching Medicare Advantage plans, moving between Medicare Advantage and Original Medicare, or changing Medicare drug coverage. Changes generally begin January 1.
Medicare Advantage Open Enrollment
People already enrolled in a Medicare Advantage plan have a separate Medicare Advantage Open Enrollment Period from January 1 through March 31. The changes permitted during this period are more limited than during the fall Open Enrollment Period.
Medigap Open Enrollment
Medigap follows different rules. Under federal law, the primary Medigap Open Enrollment Period is a one-time six-month window beginning when you are 65 or older and enrolled in Medicare Part B.
It should not be confused with the annual October 15–December 7 Medicare Open Enrollment Period.
What Should You Bring to a Medicare Consultation?
You do not need to arrive knowing which plan you want.
Bringing accurate information is much more useful.
Consider having:
- Your Medicare card or current coverage information
- A list of doctors and specialists
- A complete prescription and dosage list
- Your preferred pharmacies
- Your current plan’s Annual Notice of Change if reviewing existing coverage
- Information about employer, retiree, Medicaid, or other coverage
- Questions about travel, providers, costs, or benefits
- A family member or trusted person if you want help discussing the choices
Do not cancel existing insurance simply because another option initially appears more attractive. Review enrollment rules, effective dates, provider participation, drug coverage, and any implications for current coverage first.
Why Does Local South Florida Knowledge Matter?
Medicare itself is a federal program, but many private Medicare plan options are tied to geographic service areas.
Someone living in Coral Springs may see different Medicare Advantage or Part D choices than a family member living in another county or state.
Local comparison can therefore involve:
- Broward County plan availability
- Local physician networks
- Hospital participation
- Preferred pharmacies
- Plan-specific South Florida benefits
This is one reason our Medicare insurance assistance in Coral Springs begins with the beneficiary’s actual doctors, medications, location, and priorities rather than assuming the same option works for every senior.
Does Using a Medicare Insurance Agent Cost More?
Our consultation does not carry a separate consumer consultation fee.
For Medicare Advantage and Part D plans, Medicare allows insurers to compensate qualified agents and brokers for enrollments, subject to CMS rules. Consumers should still ask which insurance companies and plans an agency represents so they understand the scope of the comparison.
Beneficiaries who want counseling that is entirely independent of insurance sales can also contact Florida SHINE, the state’s free State Health Insurance Assistance Program.
Frequently Asked Questions About Medicare Consultations
Are iWill Advisors Medicare consultations really no cost?
Yes. We offer consultations without a separate consultation charge or obligation. Insurance agents may receive compensation from insurance companies for eligible enrollments in plans they represent. We recommend understanding both the coverage being discussed and which insurers are included in any comparison.
What is the difference between Medicare Part A and Part B?
Part A primarily covers inpatient hospital care, limited skilled nursing facility care after a qualifying inpatient stay, hospice, and certain home health services. Part B covers physician services, outpatient care, preventive services, durable medical equipment, and other medically necessary services that meet Medicare requirements.
Can a Medicare agent check whether my doctor is covered?
Yes. Provider-network participation should be reviewed when comparing Medicare Advantage plans. Because network information can change, beneficiaries should verify participation using current plan information and may also want to confirm directly with the doctor’s office before enrolling.
Should I review my prescriptions every year?
Yes. Medicare health and drug plans can change formularies, pharmacy arrangements, costs, and other plan details from one year to another. Reviewing your current medication list during annual Medicare Open Enrollment can help you evaluate whether existing coverage still meets your needs for the coming year.
Can I change Medicare plans whenever I want?
Generally, no. Medicare health and drug plan changes must usually occur during an applicable enrollment period, although Special Enrollment Periods are available in certain circumstances. The correct enrollment window depends on your current coverage, Medicare eligibility, and what change you want to make.
Is Medicare Advantage the same as Medigap?
No. Medicare Advantage is an alternative way to receive Medicare Part A and Part B benefits through a Medicare-approved private plan. Medigap supplements Original Medicare by helping pay certain out-of-pocket costs. Medigap is not designed to supplement a Medicare Advantage plan.
Can my spouse or adult child join my consultation?
Yes. A family member or trusted person can participate if you want their help asking questions, organizing information, or comparing options. Medicare coverage remains individual, however, so each beneficiary’s doctors, prescriptions, eligibility, and coverage needs should be reviewed separately.
What if I want completely unbiased Medicare counseling?
Florida’s SHINE program provides free, confidential, and unbiased Medicare counseling and is not connected to an insurance company or health plan. An insurance agency serves a different role by helping consumers compare and enroll in products offered by insurance companies the agency represents.
Schedule a No-Cost Medicare Consultation in South Florida
A productive Medicare consultation should leave you with a clearer understanding of your choices—not pressure to select a plan before you understand it.
At iWill Advisors, we help South Florida seniors and families compare Medicare Advantage, Medicare Supplement, and prescription-drug options available through the insurers we represent. We can review your doctors, prescriptions, pharmacies, costs, and coverage priorities so you can evaluate the available choices more carefully.
If you are approaching Medicare eligibility, reviewing current coverage, or preparing for an enrollment period, contact iWill Advisors to schedule a consultation or talk to our team at 954-753-8080.